UAE Small Business Relief 2029: What Businesses Need to Know About SBR Extension to 2029
The application period regarding a UAE Small Business Relief 2029 (SBR) under corporate tax has been officially extended by the UAE government.
Ministerial Decision No. 131 of 2026 amends certain provisions from Ministerial Decision No. 73 of 2023 and permitted SBR threshold as applicable to continue regarding the qualifying Tax Periods that ends on or before 31st December 2029.
This decision was delivered by the UAE Minister of State for Financial Affairs on 29th of July 2026 that became effective on the Day following its publication.
Regarding small businesses and entrepreneurs functioning in the UAE, such extensions offer more time for planning corporate tax positions with the applicable Small Business Relief framework.
Follow this guide to understand UAE Small Business Relief 2029 comprising eligibility, threshold, examples and compliance updates.
What changed under Ministerial Decision No. 131 of 2026?
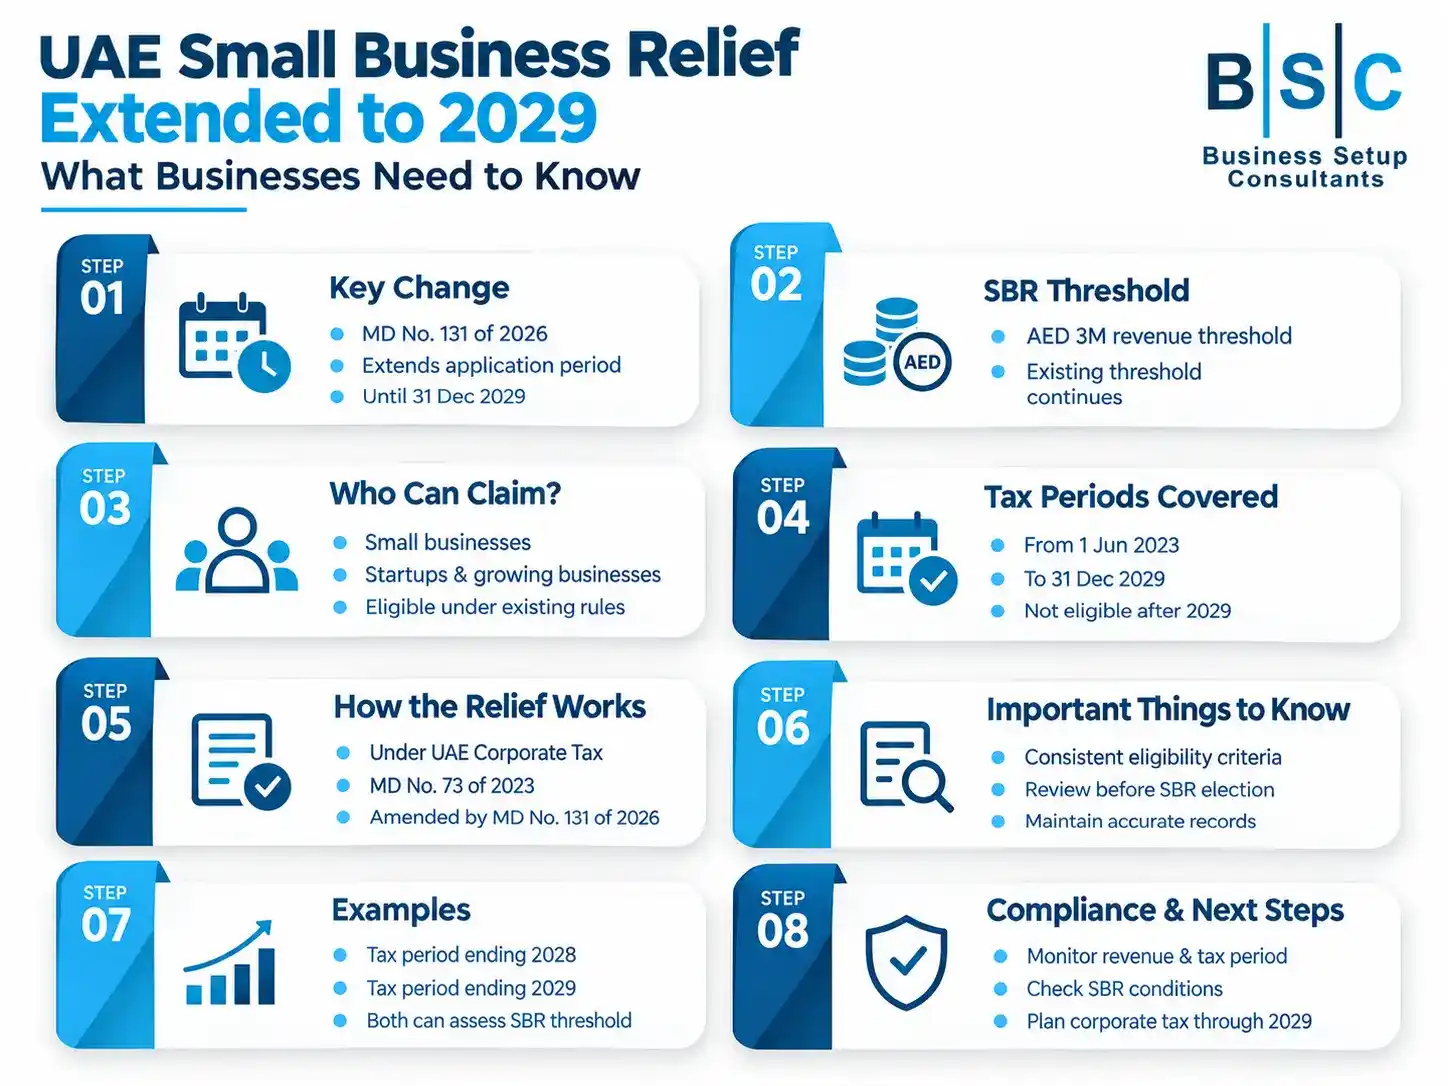
The key change has been made to Clause (2) of Article (2) of Ministerial Decision No. 73 of 2023.
The provisional amendment has confirmed that the applicable threshold will carry Tax Period consistency for:
- Commencement on or after 1st June 2023
- End on or before 31st December 2029
Previously, the threshold applied until 31st December 2026.
Now the extension has been made up to 31st December 2029 under Ministerial Decision No. 131 of 2026. This indicates that the UAE has provided an extension where the Small Business Relief thresholds can be applied consistently.
AED 3M revenue threshold
This extension has not brought a new threshold rather it has extended the period during which the existing SBR threshold becomes applicable.
For businesses expecting eligibility the significant figure is consistent at the AED 3 million Revenue threshold that was established as per the Small Business Relief framework.
It is then necessary for businesses to properly differentiate between threshold amount and the threshold applicable period.
New 31 Dec 2029 end date
The significant development for UAE businesses is the UAE Small Business Relief 2029.
Within the amended provision, the threshold is consistently applicable to subsequent tax periods ending on or before 31st December 2029.
With it, the qualifying businesses get additional time for considering a Small Business Relief to manage corporate tax obligations.
For startups and growing businesses, the extension can provide greater certainty for budget preparation, tax planning and financial forecast strategies through 2029.
Who can claim for UAE Small Business Relief 2029?
2029 extension provides eligible businesses with more time with applicable existing SBR rules.
| Key factors | What businesses need to know about UAE SBR 2029 |
| UAE Small Business Relief 2029 Eligibility | Eligibility criteria is consistent. |
| UAE Small Business Relief 2029 extension | 31st December 2029 |
| Before claiming SBR | Necessary for businesses to verify status and assure their applicable conditions. |
| 2026 Decisions | Ministerial Decision No. 131 of 2026 amending existing SBR decisions instead of replacing the framework. |
Eligible tax periods for UAE Small Business Relief 2029
| Tax period | SBR threshold application |
| Starting 1st June 2023 onwards | Threshold applies |
| Ending on or before 31st December 2029 | Threshold applies |
| After 31st December 2029 | Ineligible |
It is necessary for businesses to assess their individual tax period instead of treating 2029 as a general tax exemption.
How the relief will work under UAE Small Business Relief 2029?
The 2026 decision does not rewrite or change the entire UAE Small Business Relief 2029 framework.
| Relief area | What does it stand for? |
| Legal framework | SBR functions under UAE Corporate Tax framework |
| Existing SBR rules | Ministerial Decision No. 73 of 2023 continuing to offer a broader framework. |
| 2026 amendment | Extension of application threshold through Decision No. 131 of 2026. |
| Other requirements | Applicable compliance and existing eligibility criteria. |
Uploaded decisions particularly amends existing SBR provision with transformation of applicable end date to 31st December 2029.
Businesses that do not qualify UAE Small Business Relief 2029 Threshold
The 2029 extension does not indicate that all the small businesses qualify automatically.
| Important aspects of UAE Small Business Relief 2029 | What businesses should do |
| Consistent conditions | SBR review requirement under Decision No. 73 of 2023. |
| 2029 as no automatic exemption | Eligibility checking for relevant tax periods. |
| Limited amendment | Understanding 2026 decision as an extension of the threshold period. |
| Prior to SBR election | Confirming applicable requirements. |
The 2026 decision provides a threshold application extension and does not state broader eligibility conditions.
Examples of UAE Small Business Relief 2029
Extended timeline provides qualifying businesses with more tax periods for SBR threshold consideration.
| Example | What does it mean? |
| A business with tax period ending in 2028 | As the tax period falls under an extended period then the qualifying business can assess the applicable SBR threshold. |
| Business with tax period ending in 2029 | The qualifying business can also assess SBR threshold as decisions are extended to the tax period ending on or before 31st December 2029. |
Compliance and record-keeping for UAE Small Business Relief 2029
Extended relief period does not indicate relaxing tax records for the business.
| What to monitor | Why it matters |
| Revenue | It reflects whether the business is within the applicable threshold or not. |
| Tax period | Assurance of tax period falling within SBR timeline. |
| Financial records | Assisting accurate tax reporting as well as eligibility assessment. |
| SBR conditions | Meeting applicable requirements for the business. |
| Corporate tax compliance | Other applicable tax obligations are not removed due to extension. |
What UAE businesses should do for UAE Small Business Relief 2029?
Regarding UAE Small Business Relief 2029, it is necessary for businesses to:
- Review the tax period.
- Revenue monitoring against AED 3 million threshold.
- Check SBR eligibility conditions.
- Account record accuracy maintenance.
- Planning Corporate Tax Obligation through 2029.
- Reviewing latest UAE tax regulation prior to filing.
Conclusion
UAE Small Business Relief 2029 extension offers an important additional period for eligible businesses considering relief under the Corporate Tax framework.
The 2029 SBR extension can create valuable Tax planning opportunities for eligible UAE businesses.
If you also question your qualification and extended threshold regarding corporate tax position —
Connect with BSC and get a professional assessment for your eligibility and planning ahead.
Frequently Asked Questions (FAQs)
Can a business with AED 2.5 million revenue apply for SBR threshold in 2028?
Yes, if the business with AED 2.5 million revenue meets other applicable SBR conditions then definitely its tax period falls within the extension period of SBR 2029.
What is the AED 3 million revenue threshold for Small Business Relief 2029?
AED 3 million revenue threshold is the revenue limit for any business in the UAE to qualify for UAE Small Business Relief 2029.
What tax periods are covered by the UAE 2029 extension?
Tax period commencing on or after 1st June 2023 and ending on or before 31st December 2029 are covered under 2029 extension of the SBR.
Does Ministerial Decision No. 131 of 2026 transform the existing SBR eligibility criteria?
Only, application period of the threshold has been extended, otherwise the SBR requirements under Ministerial Decision No. 131 of 2026 are consistent.
What is the required Business Review to claim SBR?
UAE businesses are required to review revenue, tax period and eligibility criteria for maintaining accurate records for supporting their SBR position.